A Birmingham kitchen remodel, Grosse Pointe addition, or finished basement can change how a home works for years. The financing decision can shape the project just as much as the floor plan. When weighing renovation loans versus equity, homeowners need to look beyond the advertised rate and consider how the lender will handle estimates, permits, contractor payments, appraisal requirements, and the risk of borrowing against their home.
The right answer depends on the house, the amount of available equity, the scope of construction, and how quickly the work needs to begin. A smaller, contained project may call for a very different funding approach than a structural reconfiguration or whole-home renovation.
Renovation loans versus equity: the central difference
A renovation loan is financing designed to include the cost of improvements in the loan amount. Depending on the program and lender, it may be used when purchasing a home that needs work or when refinancing a home you already own. The lender typically reviews the construction plans, contractor proposal, and projected value of the completed home. Funds for the renovation are commonly held and released in stages as the work is completed.
Equity financing uses the value you already own in your home. Your equity is the difference between the home's current market value and the balance you still owe on the mortgage. A home equity loan, home equity line of credit, or cash-out refinance can convert part of that value into funds for construction.
The key distinction is timing. Renovation financing can rely in part on the home's expected value after approved improvements are complete. Equity financing generally relies on the home's current value and the equity already established. That difference matters for homeowners who have a strong project plan but limited accessible equity today.
When a renovation loan makes sense
A renovation loan can be a practical fit when the project is substantial enough to materially improve the property. Examples include opening up a load-bearing wall with proper structural framing, rebuilding an outdated kitchen, adding a bathroom, completing a basement, or buying an older home in a desirable Oakland and Macomb counties neighborhood and modernizing it before move-in.
These loans are often more structured than homeowners expect. The lender may require detailed contractor bids, a clear scope of work, permits where required, inspections, and draw requests before releasing funds. That structure can feel demanding, but it also creates a documented path for a major project with several trades involved.
For a homeowner purchasing a house that needs major work, renovation financing can avoid the problem of buying the property first and then trying to find separate funds for construction. It may also be useful where a home has not yet built enough equity to support the planned investment.
There are trade-offs. Approval may take longer because the lender has to evaluate more than personal credit and income. Changes made after closing can also be more difficult to accommodate. If the original scope omits demolition, mechanical updates, structural repairs, or permit costs, the homeowner may need to cover those additions from a contingency reserve or another source.
A renovation loan works best when the construction scope is defined before work begins. That means decisions about layout, materials, engineering, and permitting should not be left until crews are ready to start. Early planning protects both the budget and the financing timeline.
Why contractor documentation matters
Lenders do not finance a vague idea such as “update the first floor.” They commonly need a proposal that separates labor and materials, identifies major work categories, and aligns with the appraisal and draw process. For larger projects, they may also want plans, specifications, insurance information, and permit details.
A qualified builder can help turn a homeowner's goals into a workable project scope. This is especially valuable for older homes throughout Oakland County, Macomb County, and Oakland-Macomb area communities, where a cosmetic renovation can uncover outdated wiring, water damage, undersized framing, or code-related requirements. A realistic scope gives the lender a better picture of what the project will actually require.
When using home equity may be the better route
Equity financing may be simpler for homeowners who have owned their property for years, have meaningful available equity, and want more control over when and how funds are used. A home equity loan provides a lump sum, usually with a fixed repayment structure. A HELOC provides a credit line that can be drawn as needed, often during a set draw period. A cash-out refinance replaces the current mortgage with a larger one and provides the difference as cash.
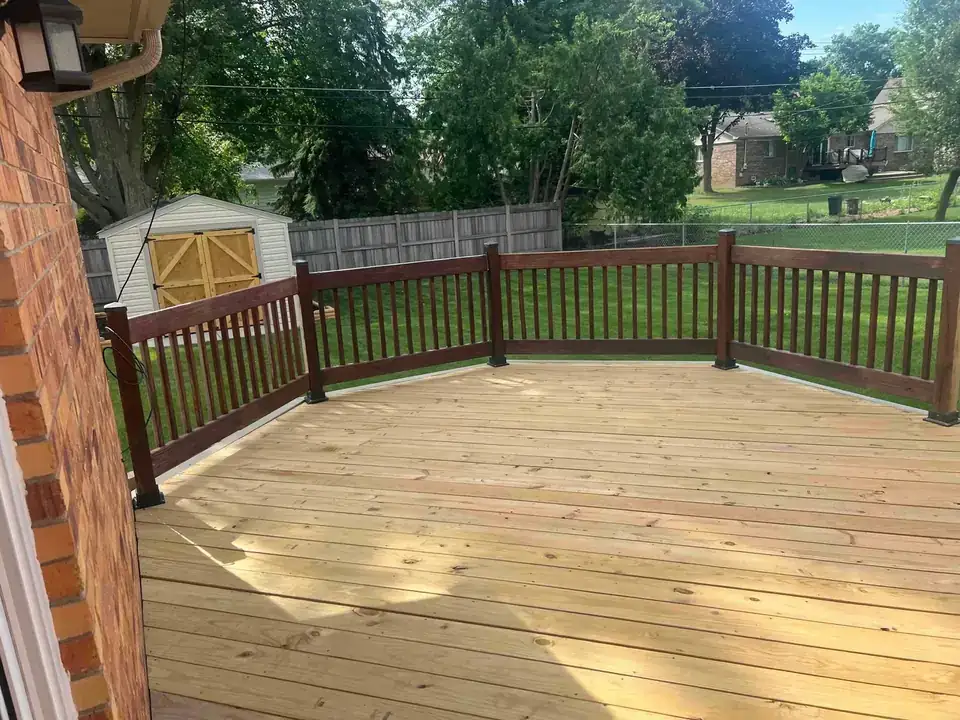
For a deck, basement remodel, kitchen renovation, or phased home improvement plan, access to equity may offer more flexibility than a tightly administered renovation loan. Once funds are available, the homeowner and contractor can manage payment milestones based on the construction agreement rather than a lender's inspection schedule.
That flexibility is useful, but it requires discipline. A homeowner should keep the construction budget separate from general household spending, retain a contingency amount, and understand exactly how payments will be released. Large deposits without a written scope, schedule, and permit plan can create avoidable risk regardless of the financing method.
A cash-out refinance deserves particularly careful review. If the existing mortgage has a low fixed rate, replacing the entire loan could raise the rate on the full outstanding balance, not just the amount needed for renovations. A home equity loan or HELOC may preserve the original first mortgage, though the rates, terms, fees, and monthly payment requirements still need to be compared carefully.
Compare the full cost, not just the interest rate
The lowest initial rate is not always the lowest-cost choice. Homeowners should compare interest rates, closing costs, appraisal fees, loan terms, monthly payment changes, and whether the rate is fixed or variable. They should also ask how long the lender expects approval, closing, and access to construction funds to take.
With a renovation loan, ask whether contractor draws are required, who orders inspections, and how long it takes for approved draw funds to be released. Construction crews, suppliers, and specialty trades need dependable payment timing. Delays in funding can delay the project.
With equity financing, ask whether the line has a variable rate, whether there are annual fees or early closure fees, and how the payment changes when the draw period ends. A HELOC can be useful for a project completed in phases, but a variable payment may be less comfortable for a homeowner who needs predictable long-term costs.
Also consider the project value. Not every dollar spent on construction creates an equal increase in appraisal value. A well-planned kitchen, added living space, corrected structural issue, or permitted basement finish may support long-term marketability. Highly customized finishes may improve daily life without returning their full cost at resale. Finance the project for both the home's value and your intended use of it.
Match the financing to the construction scope
A defined, major renovation with a complete plan often aligns well with a renovation loan. A project where the after-renovation value helps support borrowing may benefit from that approach, particularly for a purchase-and-renovate situation.
Existing homeowners with strong equity and a straightforward construction plan may prefer a home equity loan or HELOC. This can be a sensible route when the work will be completed in stages or when the homeowner wants to keep lender involvement out of day-to-day draw decisions.
For a major addition, whole-home reconfiguration, or custom build-level project, do not assume a standard equity product will cover every need. The total budget may include design, engineering, demolition, permits, site work, framing, mechanical trades, finishes, and contingency. Discuss the full project cost before choosing financing, rather than selecting a loan amount based only on the first visible phase.
Plan the project before applying
Whether you choose equity financing or a renovation loan, the strongest applications start with organized information. Have a preliminary scope, contractor estimate, realistic allowance for selections, and a contingency for conditions discovered after demolition. Confirm which permits are required and who will handle them. For structural work, make sure engineering and framing requirements are addressed before construction pricing is finalized.
It is also wise to review the household budget as honestly as the construction budget. Account for the new payment, property taxes, insurance changes if applicable, and the possibility that part of the home may be unavailable during construction. Financing should support a project you can complete properly, not force rushed decisions once the walls are open.
Christian Wylie LLC helps homeowners across Oakland County, Macomb County, and the five Grosse Pointes organize substantial renovations with the practical scope, trade coordination, permit awareness, and construction management those projects require. Before deciding how to fund the work, get a detailed estimate that reflects the home you have and the finished space you want to live in.