A kitchen renovation, basement finish, addition, or major exterior upgrade can improve how your home works for your family - but the financial plan needs to be as organized as the construction plan. The right financing options for home renovation depend on your available equity, credit profile, project timeline, and how much flexibility you need once walls are opened and work begins.
For homeowners across Oakland County, Macomb County, and the five Grosse Pointes, the first step is not choosing a loan. It is defining the actual scope of work. A budget for paint and flooring is different from a budget that includes demolition, structural framing, electrical upgrades, plumbing relocation, permits, and inspections. Financing should support the full project, not just the most visible finish selections.
Start With a Complete Renovation Budget
Before applying for financing, ask for a detailed project estimate that separates the major parts of the job. For a substantial renovation, that commonly includes design or planning, permits, demolition, framing, mechanical work, insulation, drywall, finishes, labor, and construction management. If your home is older, allow room for conditions that may only become visible after demolition, such as outdated wiring, water damage, or framing repairs.
A realistic budget also includes a contingency. Many homeowners set aside 10% to 20% for unforeseen work, with the appropriate amount depending on the age and complexity of the home. A simple deck replacement may need less flexibility than a whole-home renovation involving walls, plumbing, or structural changes.
Do not finance only the contractor's base proposal and assume the rest will work itself out. Include permit fees, material allowances, temporary living arrangements if needed, and the reserve that helps prevent a change in plan when an unexpected condition is discovered.
Financing Options for Home Renovation: How They Compare
No single funding method is right for every project. The best fit often comes down to whether you want predictable payments, access to funds over time, or the lowest possible borrowing cost.
Paying With Cash
Cash is the most straightforward option for homeowners with sufficient savings. There is no interest, no lender underwriting, and no monthly loan payment after construction is complete. It can also make the payment process simpler when a project is completed in scheduled construction phases.
The trade-off is liquidity. Draining emergency savings to pay for a renovation can leave a household exposed to medical expenses, job changes, property repairs, or other unexpected costs. Paying cash is usually strongest when it still leaves a healthy reserve after the project is funded.
Home Equity Line of Credit
A home equity line of credit, commonly called a HELOC, lets qualified homeowners borrow against available equity up to an approved limit. During the draw period, you can typically access funds as needed rather than taking the entire amount at once. That can suit a renovation with multiple stages or a project where final costs may shift within an agreed contingency range.
HELOCs often have variable interest rates, which means payments can increase if rates rise. They may also carry lender fees, annual fees, or requirements related to the first mortgage. Homeowners should understand the draw period, repayment period, rate structure, and whether the lender can change the available credit terms.
Home Equity Loan
A home equity loan is usually a lump-sum loan secured by your home. It commonly has a fixed interest rate and fixed monthly payments, making it easier to build into a household budget. For a clearly defined project - such as a finished basement, major kitchen remodel, or new deck - that predictability can be valuable.
Because the loan is secured by the property, lenders evaluate equity, income, debt, and credit. The risk is equally clear: your home secures the debt. Borrow only what you can reasonably repay, even if the lender approves a larger amount.
Cash-Out Refinancing
A cash-out refinance replaces your existing mortgage with a new, larger mortgage and provides the difference in cash for the renovation. It may make sense if current refinancing terms are favorable compared with your existing mortgage and other borrowing options.
However, this choice deserves careful review. Refinancing can restart the mortgage term, involve closing costs, and replace a low existing interest rate with a higher one. For homeowners who locked in a favorable first-mortgage rate, a separate equity loan or HELOC may be more practical. Compare the total long-term cost, not just the monthly payment.
Personal Loans
An unsecured personal loan does not use your home as collateral. Approval and rates are generally based on credit, income, and debt-to-income ratio. The application process can be faster than a home equity product, and funds may be useful for smaller, defined improvements.
The convenience can come with higher interest rates and shorter repayment terms. For a large renovation involving structural work or extensive trade coordination, the monthly payment may be much higher than a secured financing option. Personal loans are often better suited to modest projects or to covering a limited gap in a broader funding plan.
Contractor or Lender Financing Programs
Some qualified contractors offer access to third-party financing programs for larger home improvement investments. These programs can give homeowners another path to apply for financing while planning the work, but the loan is still a financial product that requires careful comparison.
Review the annual percentage rate, promotional-rate period, fees, repayment term, prepayment rules, and what happens when a promotional period ends. Do not make a decision based only on a low introductory payment. Ask whether the financing amount, approval timing, and funding process align with the contractor's payment schedule and your construction start date.
Match the Funding Method to the Work
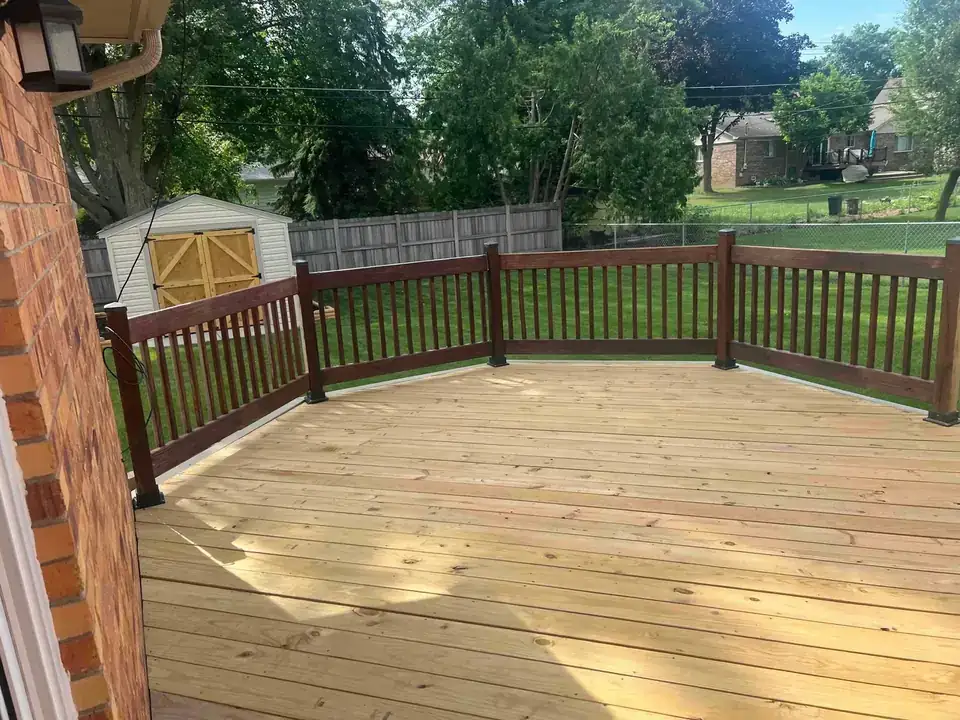
The size and nature of the renovation should guide the financing discussion. A homeowner replacing a deck may prioritize a fixed loan with a clear payoff schedule. A family planning a phased renovation of an older Birmingham or Grosse Pointe home may value the flexibility of a line of credit, especially if the work includes demolition and structural discovery.
For a full renovation, addition, or custom-build-related work, it is especially important to coordinate financing before contracts are finalized. Larger projects often progress through deposits and milestone payments tied to materials, inspections, framing, mechanical work, and completion. Your financing needs to make funds available when those legitimate project costs occur.
Avoid using the least expensive-looking option without considering timing. A loan with a low rate but a slow closing process may not help if you need to order long-lead materials. On the other hand, fast financing with a high rate can add significant cost to a project that will take months to complete.
Questions to Ask Before You Sign
Ask every lender for the annual percentage rate, not only the interest rate. APR provides a clearer view of borrowing costs because it can reflect certain fees. Confirm whether the rate is fixed or variable, how long the repayment term lasts, the estimated monthly payment, and whether there is a penalty for paying the loan off early.
You should also ask how funds are released. Some loans provide a lump sum, while others allow draws over time. If lender inspections or contractor documentation are required before a draw, understand that process before construction starts. A payment delay can affect material orders and the project schedule.
Finally, keep the construction agreement and financing agreement separate in your review. Make sure you understand the scope of work, allowances, payment milestones, change-order process, permit responsibilities, and warranty terms on the construction side. Financing should make a well-planned project possible; it should not substitute for a clear contract and qualified execution.
Build the Project Plan Before the Payment Plan
A renovation is a long-term investment in the home, but it is also an active construction process with real decisions along the way. Choosing a licensed, insured contractor with experience in permits, framing, demolition, and trade coordination helps you establish a scope that lenders and homeowners can evaluate with confidence.
Christian Wylie LLC can provide a free estimate for homeowners planning significant renovations, basement remodeling, decks, structural improvements, and custom residential work across Oakland and Macomb counties. Bring your financing questions into the planning conversation early. A clear estimate, realistic contingency, and payment schedule give you a stronger foundation before construction begins.